Aaron McIntosh thought he was following the rules of the Avis Uber Partner Program until his bank flagged the rental company’s aggressive billing as fraud. By the time he was able to explain the situation, Avis had repossessed the car and banned him for life. Can a consumer advocate get this driver back on the road?
Question
I was renting a car through the Avis Uber Partner Program so I could drive for Uber. The arrangement was simple: it cost $349 a week, which was supposed to be deducted from my bank account.
But things went south when Avis started charging my card for different amounts, several times a day. My bank, assuming this was fraudulent activity, blocked Avis and locked my account for security.
This created a major problem. I had to wait for a new card to be issued and mailed to me, which meant I couldn’t access my funds to make my weekly payment on time. I didn’t go silent, though. I communicated this clearly to the Avis office where I rented the vehicle, through a text line provided to drivers. I also spoke with a representative from the Recovery Team who said she would note my account.
He asked “Should I return the car?” and a staff member told him to “text when you’re ready.” That response is extremely unclear and he should have asked for clarification.
I can see an interpretation of “keep it and let us know when you want to return it,” and I can also see an interpretation of “yes, return it, and let us know when you have it ready.” It’s a yes or no question and the response is not yes or no.
I explicitly asked an Avis representative if I should keep the vehicle until my new card arrived. or if I could pay via Bill Pay. He didn’t tell me to bring the car back; he just replied, “Text when you’re ready.” I took that to mean I was okay to keep the car until the card arrived.
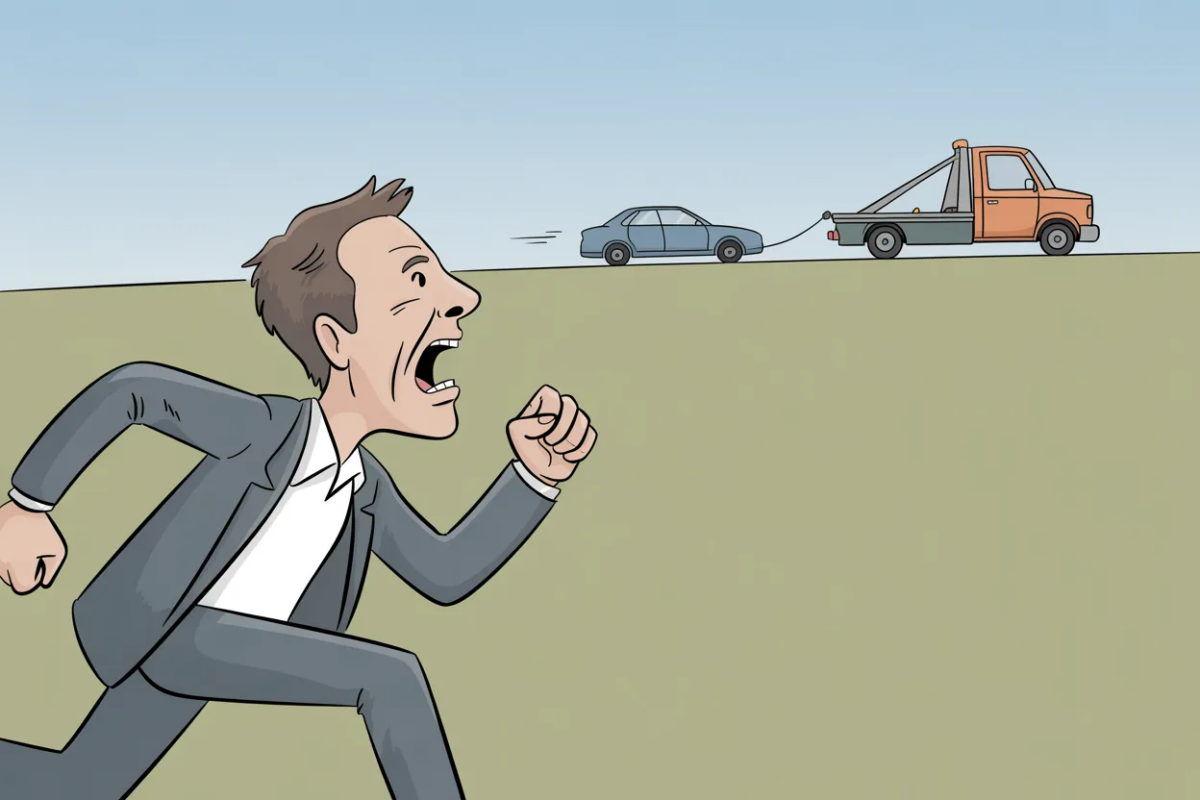
A day or two later, as I was getting into the car to go to the office and pay, I saw a tow truck drive past with the car I had been renting. I followed him and waved him down at a red light. It was Avis coming to repossess the car. The company called it a repossession even though I had provided payment for the previous two weeks.
Now, Avis has placed me on its “Do Not Rent” list for two years, claiming the payment was 14 days overdue and that its Loss Prevention department had to step in. This ban effectively ends my ability to earn a living as an Uber driver. I’ve already paid the outstanding balance in full, including $1,895 in additional charges and fees. I just want to be removed from the DNR list so I can get back to work. — Aaron McIntosh, Philadelphia
Answer
Avis should have read its own notes in your records. When a customer explicitly asks, “Should I return the car?” and a staff member tells them to “text when you’re ready,” the company shouldn’t call the repo man.
(Before I continue, just a note about your case. I normally handle consumer disputes in this column. But your billing issue has broader applications, so my advocacy team and I decided to handle your case, even though technically you’re a business.)
While rental companies have a right to protect their assets, they also have an obligation to provide clear instructions to their customers. If a payment fails because of a bank’s fraud detection—triggered by the company’s own erratic billing patterns—a little human intervention would be helpful. Unfortunately, you didn’t get any.
You established a paper trail early by texting the office and followed up with the Avis recovery team. However, “text when you’re ready” is dangerously vague.
When you’re dealing with a rental company, if you can’t pay, return the car immediately to the lot, get a bill, and then wait for your new debit card.
If you ever find yourself blacklisted, you can appeal the decision to the executives at Avis. I publish their contact information on my advocacy site, Elliott.org.
I contacted Avis on your behalf to see if it could take a second look at your case. The company’s security team performed a manual review of your account.
“Our records indicate that we’ve received a response from our security team confirming that all outstanding fees had been paid and that his removal from the DNR list was authorized,” a representative from Avis told me.
You’re now off the Do Not Rent list and free to rent again. Just two tips for the future: First, let your bank know about your arrangement with Avis so it can whitelist the transactions. And if your bank still flags your car rental payment as a crime spree, it might be time to switch to a credit card—or a different bank.

Have a question about this story? Tell us what happened — we read every comment.
Join the conversation